Norwegian salmon-farming and seafood-processing company Hofseth saw its revenue drop heavily in Q3 2026, dragging down its net profit with it.
Hofseth posted revenue of NOK 859 million (USD 88 million, EUR 80.1 million) in Q3 2026, down 46 percent from the NOK 1.58 billion (USD 161.8 million, EUR 147.3 million) it posted in the same period of 2025. Group EBITDA also dropped to NOK 80.3 million (USD 8.2 million, EUR 7.5 million) from NOK 179 million (USD 18.3 million, EUR 16.7 million).
Overall, net losses for the period reached NOK 49.6 million (USD 5.1 million, EUR 4.6 million), a drop from the losses of NOK 5.2 million (USD 532,000, EUR 484,900) that the company posted in Q3 2025.
The company said the reduction in revenue was largely related to lower contracted volumes in Hofseth’s processing division. Revenue in the processing segment dropped heavily in Q3, decreasing by 54 percent, or NOK 797.2 million (USD 81.6 million, EUR 74.3 million), to NOK 691.7 million (USD 70.8 million, EUR 64.5 million).
“This development is a consequence of the challenging contract market during the second half of 2025, which resulted in fewer contracts being secured compared with previous years,” Hofseth said.
The processing segment reported EBITDA of NOK 72.5 million (USD 7.4 million, EUR 6.8 million) in the quarter, a 55 percent decrease from the NOK 161.2 million (USD 16.5 million, EUR 15 million) it posted in the same period of the prior year.
Total processing volume dropped to 9,724 metric tons (MT) in the quarter, down from 16,939 MT in Q3 2025. Those lower volumes resulted in higher unit costs and were the main driver of the segment's weak results, the company said.
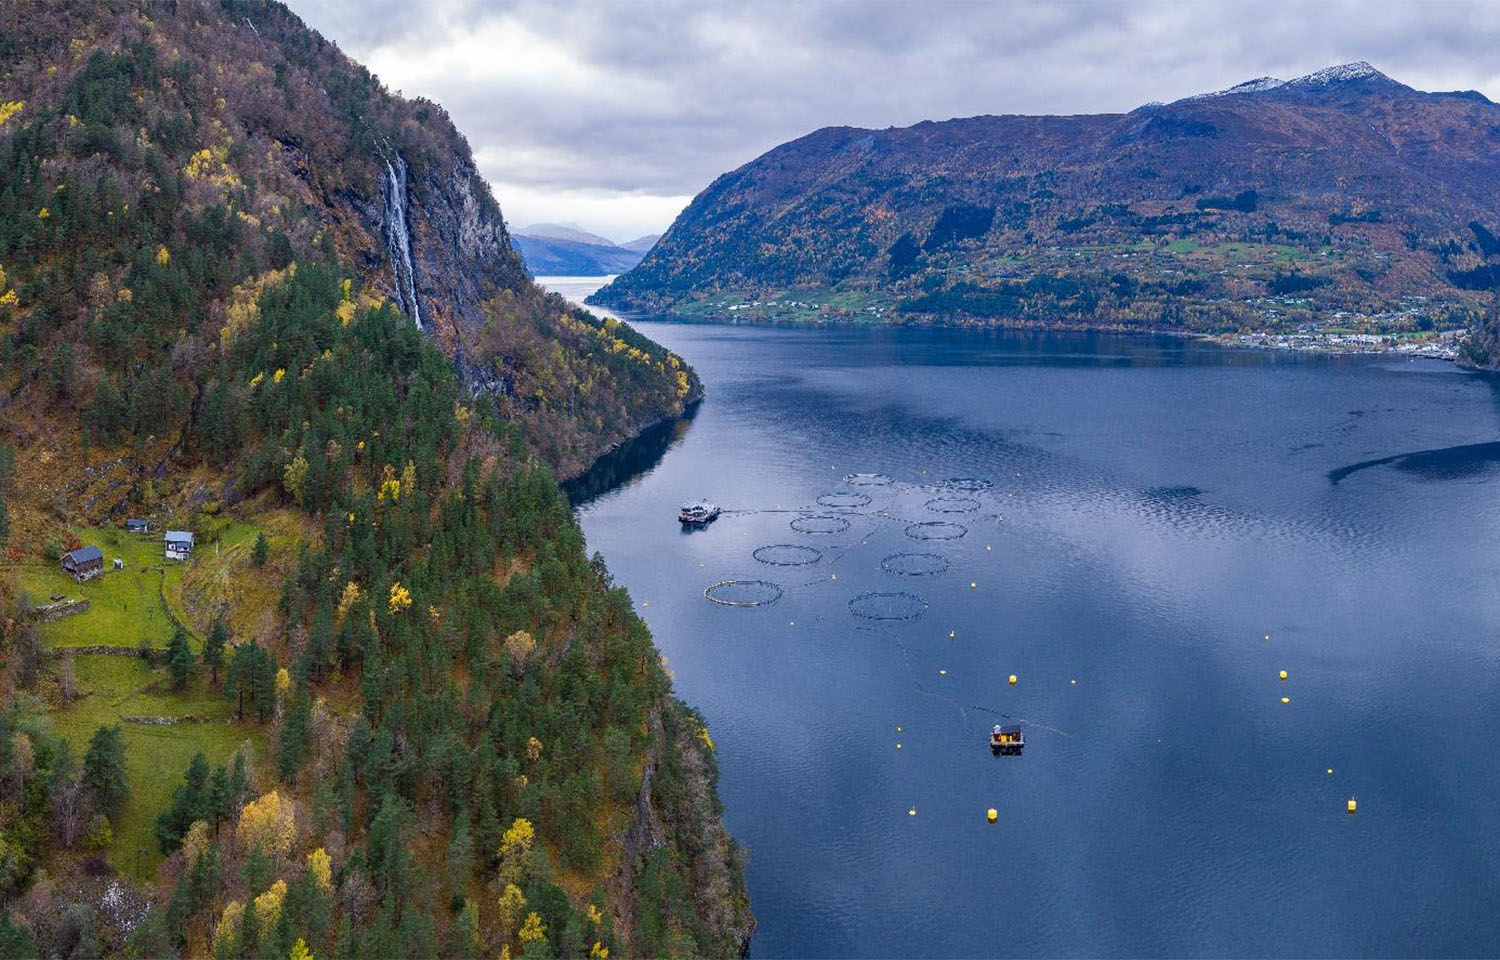
As the company’s processing segment saw losses, its farming segment began to see upticks in revenue.
The company’s farming segment saw its revenue increase by NOK 31.3 million (USD 3.2 million, EUR 2.9 million), or 12 percent, to NOK 300.9 million (USD 30.8 million, EUR 28.1 million) in Q3 2026, which the company said was driven by higher volumes and higher sales prices.
According to Hofseth, harvests increased to 4,411 MT of head-on gutted (HOG) fish, up from 4,269 MT of HOG fish in Q3 2025. Those harvests are split between salmon and trout, with salmon accounting for 52 percent of the quarter’s harvest volume and trout accounting for the other 48 percent.
Overall harvest weights also increased 5 percent year over year, which was largely driven by a 29 percent increase in the harvest weight of trout.
Standing biomass at the end of Q3 was 6,021 MT, a drop of 3.1 percent compared to the same period of 2025 and a drop of 13 percent compared to Q2 2026. The company also said utilization of its ordinary licenses was 91 percent, while it dropped to 15 percent for its R&D licenses.
“The lower utilization reflects the early harvesting of one cohort following a decision made on fish health grounds,” the company said.
While the farming division posted solid harvests and revenue, its EBITDA dropped to NOK 7.8 million (USD 798,700, EUR 727,400) from NOK 17.7 million (USD 1.8 million, EUR 1.7 million) a year ago, which the company said reflects a decrease in gross margin. EBIT costs reached NOK 72.4 (USD 7.41, EUR 6.75) per kilogram, which the company said was an increase of 11 percent year over year.
Looking forward, Hofseth said 2026 continues to be a “very challenging year” for its processing division and for the wider European salmon-processing industry. However, it said the contract negotiation period with most of its key customers has concluded and the company “expects significant growth in contracted volumes across the U.S., Europe, and Asia markets for 2027.”
Hofseth said early indications are that processing volume in 2027 will reach at least 47,000 MT, which would be up from the 37,000 MT expected in 2026.
