
Global aquaculture output is expected to keep growing in 2027, but according to Rabobank’s latest sector outlook, that additional production will be increasingly concentrated in lower-value species and emerging markets, while more mature, higher-value species such as Atlantic salmon, sea bass, and sea bream are losing momentum.
The “Global Aquaculture Outlook 2027” report, compiled by RaboResearch analysts Novel Sharma and Gorjan Nikolik, is based on a survey run in collaboration with the Global Seafood Alliance (GSA), supplemented by Kontali data for salmon, cod, sea bass, and sea bream. The survey forecast pangasius output to rise 6 percent in 2027, shrimp growth of 5 percent, and tilapia output increasing 4 percent. However, it also forecast just 2 percent growth for salmon, sea bass, and sea bream.
The analysis blames softer demand in Western markets, persistent inflation, geopolitical uncertainty, and elevated fishmeal and feed costs for the more cautious outlook in higher-value species.
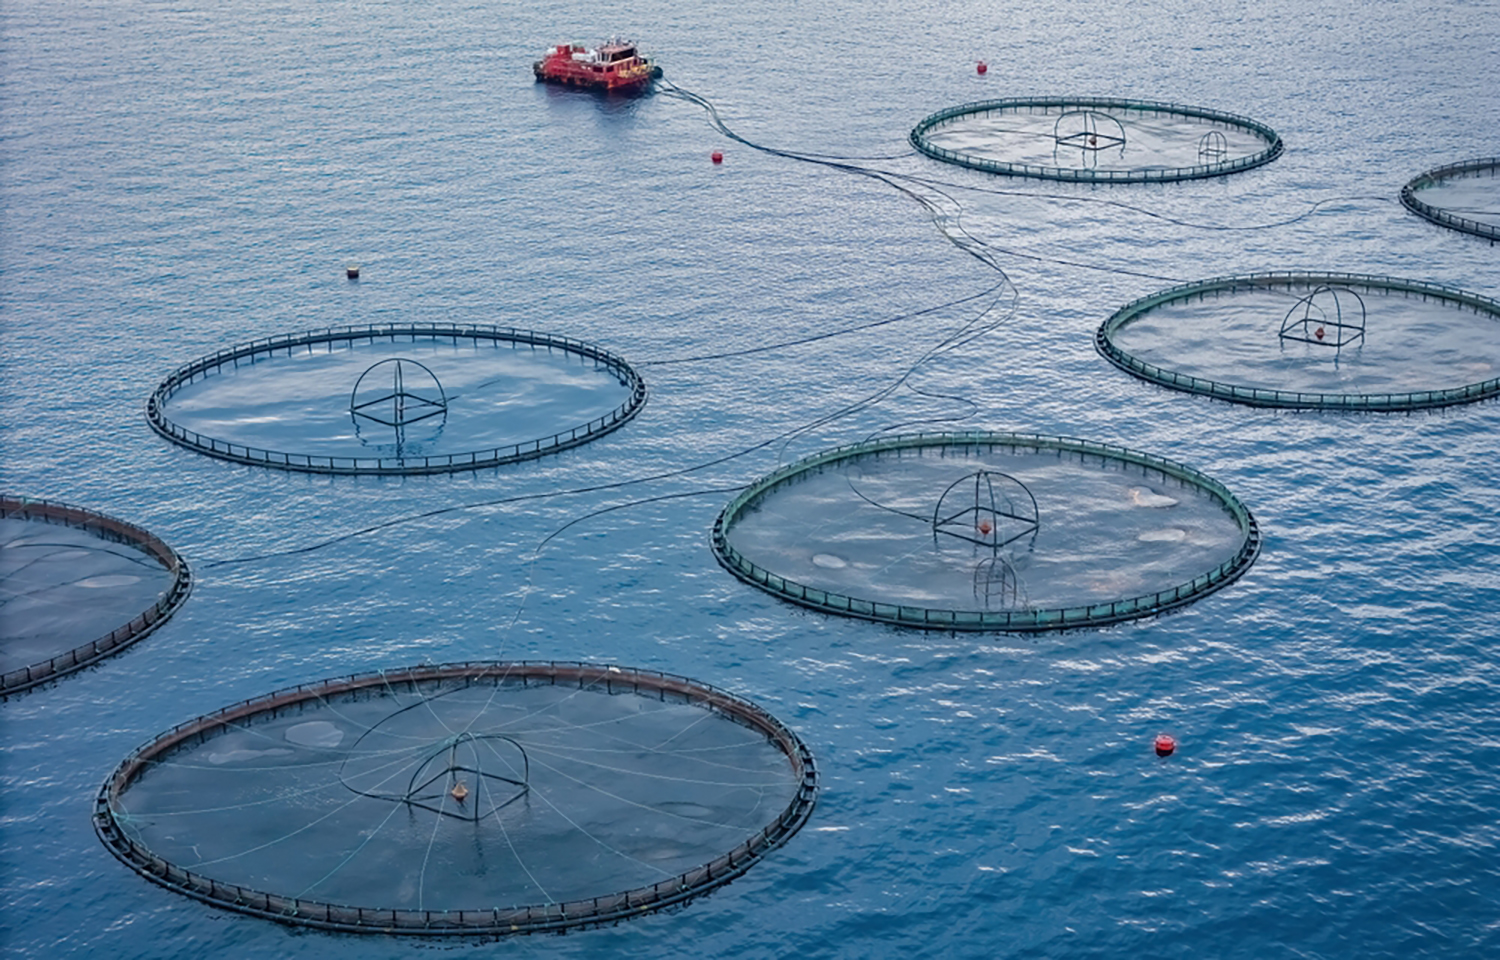
Regarding Atlantic salmon in particular, the report described the market as shifting from oversupply to tight supply. For instance, global production rose 11.9 percent in 2025 but is forecast to grow just 3.1 percent in 2026 and 1.5 percent in 2027 before recovering to 2.6 percent in 2028.
The report pointed to the fact that Norway’s exceptional biological gains over the past two years will likely be hard to repeat in 2027, as well as the fact that regulatory and biomass limits will start to bite.
Sharma told SeafoodSource more specifically that harvest volumes in September and October of this year had exceeded those in the same months of 2025, leaving fewer fish in the sea heading into Q1 2027.
“This is expected to constrain harvest potential in late 2026 and early 2027,” Sharma said.
The world’s second top salmon-farming nation, Chile, experienced 15 percent production growth in 2025, amounting to 807,000 metric tons (MT), and is expected to see broadly flat growth in 2026 before rising to about 2 percent in 2027 to 820,000 MT aided by higher smolt stocking. Rabobank’s report flags El Niño in the 2026-27 season as a risk, but it said the industry is far better prepared than it was during previous such weather patterns.
Elsewhere, salmon growth is expected to be uneven.
Iceland’s salmon harvest is forecast to rise 29 percent in 2026 and 7 percent in 2027. Output from the U.K., comprising Scottish operations, is set to grow 4 percent in 2026 and 2 percent in 2027, accelerating to 6 percent in 2028. Canada is forecast to fall 6 percent in 2026 before recovering by the same margin in 2027, and the Faroe Islands is expected to dip 1 percent next year before rising 2 percent in 2028.
Sharma advised that a tighter salmon supply-demand balance is likely to support prices and margins across the board.
“In recent quarters, weaker demand and increased supply have pushed prices lower,” he said. “As supply growth normalizes after two years, prices are expected to recover unless demand contracts significantly.”
Switching species, Norwegian farmed Atlantic cod is forecast to grow 21.4 percent in 2026, 14 percent in 2027, and 8.8 percent in 2028, according to the GSA survey. Rabobank forecasts an output of around 31,000 MT by 2028, which would more than double totals of around 15,000 MT in 2024.
The report noted that cod farming has twice faltered in Norway, but today’s economics provide a more promising outlook. Prices have reached unprecedented levels thanks to historically low Barents Sea wild cod quotas, and farmed cod now sells at prices comparable to, and sometimes above, farmed salmon. Better selective breeding and feed conversion ratios, as well as progress on cannibalism and early maturation, have eased biological problems that occurred in the sector’s infancy.
However, Rabobank’s analysis cautioned that the sector is still in its relative early stages, and execution risks should not be underestimated as the industry aims to mature.
Global shrimp production, meanwhile, is forecast to grow 3.8 percent in 2026 and 4.9 percent in 2027.
Ecuador remains the top global producer, with an output forecast to rise more than 15 percent in 2026 to above 1.6 million MT – ahead of earlier estimates of around 10 percent.
“Sustaining this pace, however, is becoming more challenging,” the analysis said, pointing to rising feed and diesel costs.
India’s shrimp production is forecast to pass 1 million MT in 2027, which would mark 8 percent growth. Vietnam and Indonesia are expected to experience weaker growth, with Indonesia forecast to fall 6 percent in 2026 and 3 percent in 2027. Mexico is expected to contract 9 percent in 2026 before rebounding to 15 percent growth next year.
“The industry still appears optimistic about supply growth in 2027,” Sharma said. “Oversupply has kept prices low, while import volumes have been volatile as surplus production shifts between destination markets. However, since fixed costs are increasing in some regions, expanding production to spread it out to limit impact on unit cost might be a potential reason why production is still expected to expand despite an oversupply situation.”
Tariffs are also driving greater diversification in product formats across the global shrimp sector, as each of the major global buyers has different preferences, Sharma said.
“I expect trade flows to continue shifting in the short term. China and the U.S. are likely to remain the primary buyers, but their relative importance may vary throughout 2027. Imports from most supplying regions may shift toward China in some periods and toward the U.S. in others,” he said. “Compared with salmon, shrimp is mostly traded frozen and is more commoditized, giving buyers greater flexibility to switch suppliers based on price. Tariffs, however, may alter producers’ relative competitive advantages.”
Global pangasius production is expected to approach 4 million MT in 2027. Vietnam – at more than 2 million MT – remains the frontrunning producer, but India is the main growth driver, expected to account for about 48 percent of incremental supply in 2027 as output nears 1 million MT.
“Rising local demand is supporting production growth as the country gradually emerges as a larger seafood-consuming market, supported by rising incomes and more diversified animal protein consumption,” Rabobank’s analysis said.
Tilapia is forecast to pass 8 million MT, with growth shifting to the Global South. Output in Uganda, Ghana, Nigeria, Zambia, and Kenya combined is forecast to rise 13 percent in 2026 and 17 percent in 2027.
Egypt, Africa’s largest producer at around 1.2 million MT, is expected to grow less than 1 percent a year as water shortages and rising temperatures constrain expansion. Away from Africa, China is expected to grow around 1 percent as high feed costs squeeze margins.
Mediterranean sea bass and sea bream growth is forecast to slow from 5 percent to 6 percent in 2025 to 1 percent in 2026 and 2 percent in 2027, taking the output from 584,000 MT in 2024 to around 634,000 MT by the end of next year. Turkey is expected to remain flat in 2026, Greece to grow 1 percent, and Spain to shrink 1 percent.
In China, output of pompano, large yellow croaker, grouper, Japanese sea bass, and turbot is forecast to grow about 8 percent a year in 2026 and 2027, passing 1.5 million MT for the first time in 2027.
Among the survey respondents, aquafeed costs, market prices, and disease prevention remain top concerns. Respondents are slightly more optimistic about 2027 than they were last year about 2026, though less confident that feed prices will fall.
